Arroyo Bend
Commons
| To | Elena Park, Graham Oduya | Date | August 24, 2026 |
| From | Calder Ridge Partners, capital markets | Basis | 10-year model, 5-year hold |
Open at $11.26M. Approve to $12.18M. Walk above $12.76M.
The deal underwrites at a $12,180,000 basis for the center and all five pad lots, but the marketed 8.18% cap does not survive our assumptions. Our Year 1 NOI is $703,437, a 5.78% going-in, or 7.24% on the center alone with the land held at its $2,465,000 ask.
The value-add case carries the return. Leasing 22,248 SF of vacancy and converting gross leases to NNN at rollover takes NOI to $1,221,348 by Year 3. On a 5-year hold at a 7.50% exit that is an 11.1% unlevered IRR and 1.64x. We would open at $11,258,000, which pays the full ask on the pads and an 8.00% on the operating center.
Hover a price for going-in, Year 3 yield, IRR and multiple. The center alone is marketed at $11,185,000, an 8.18% cap on the seller's $914,568 NOI.
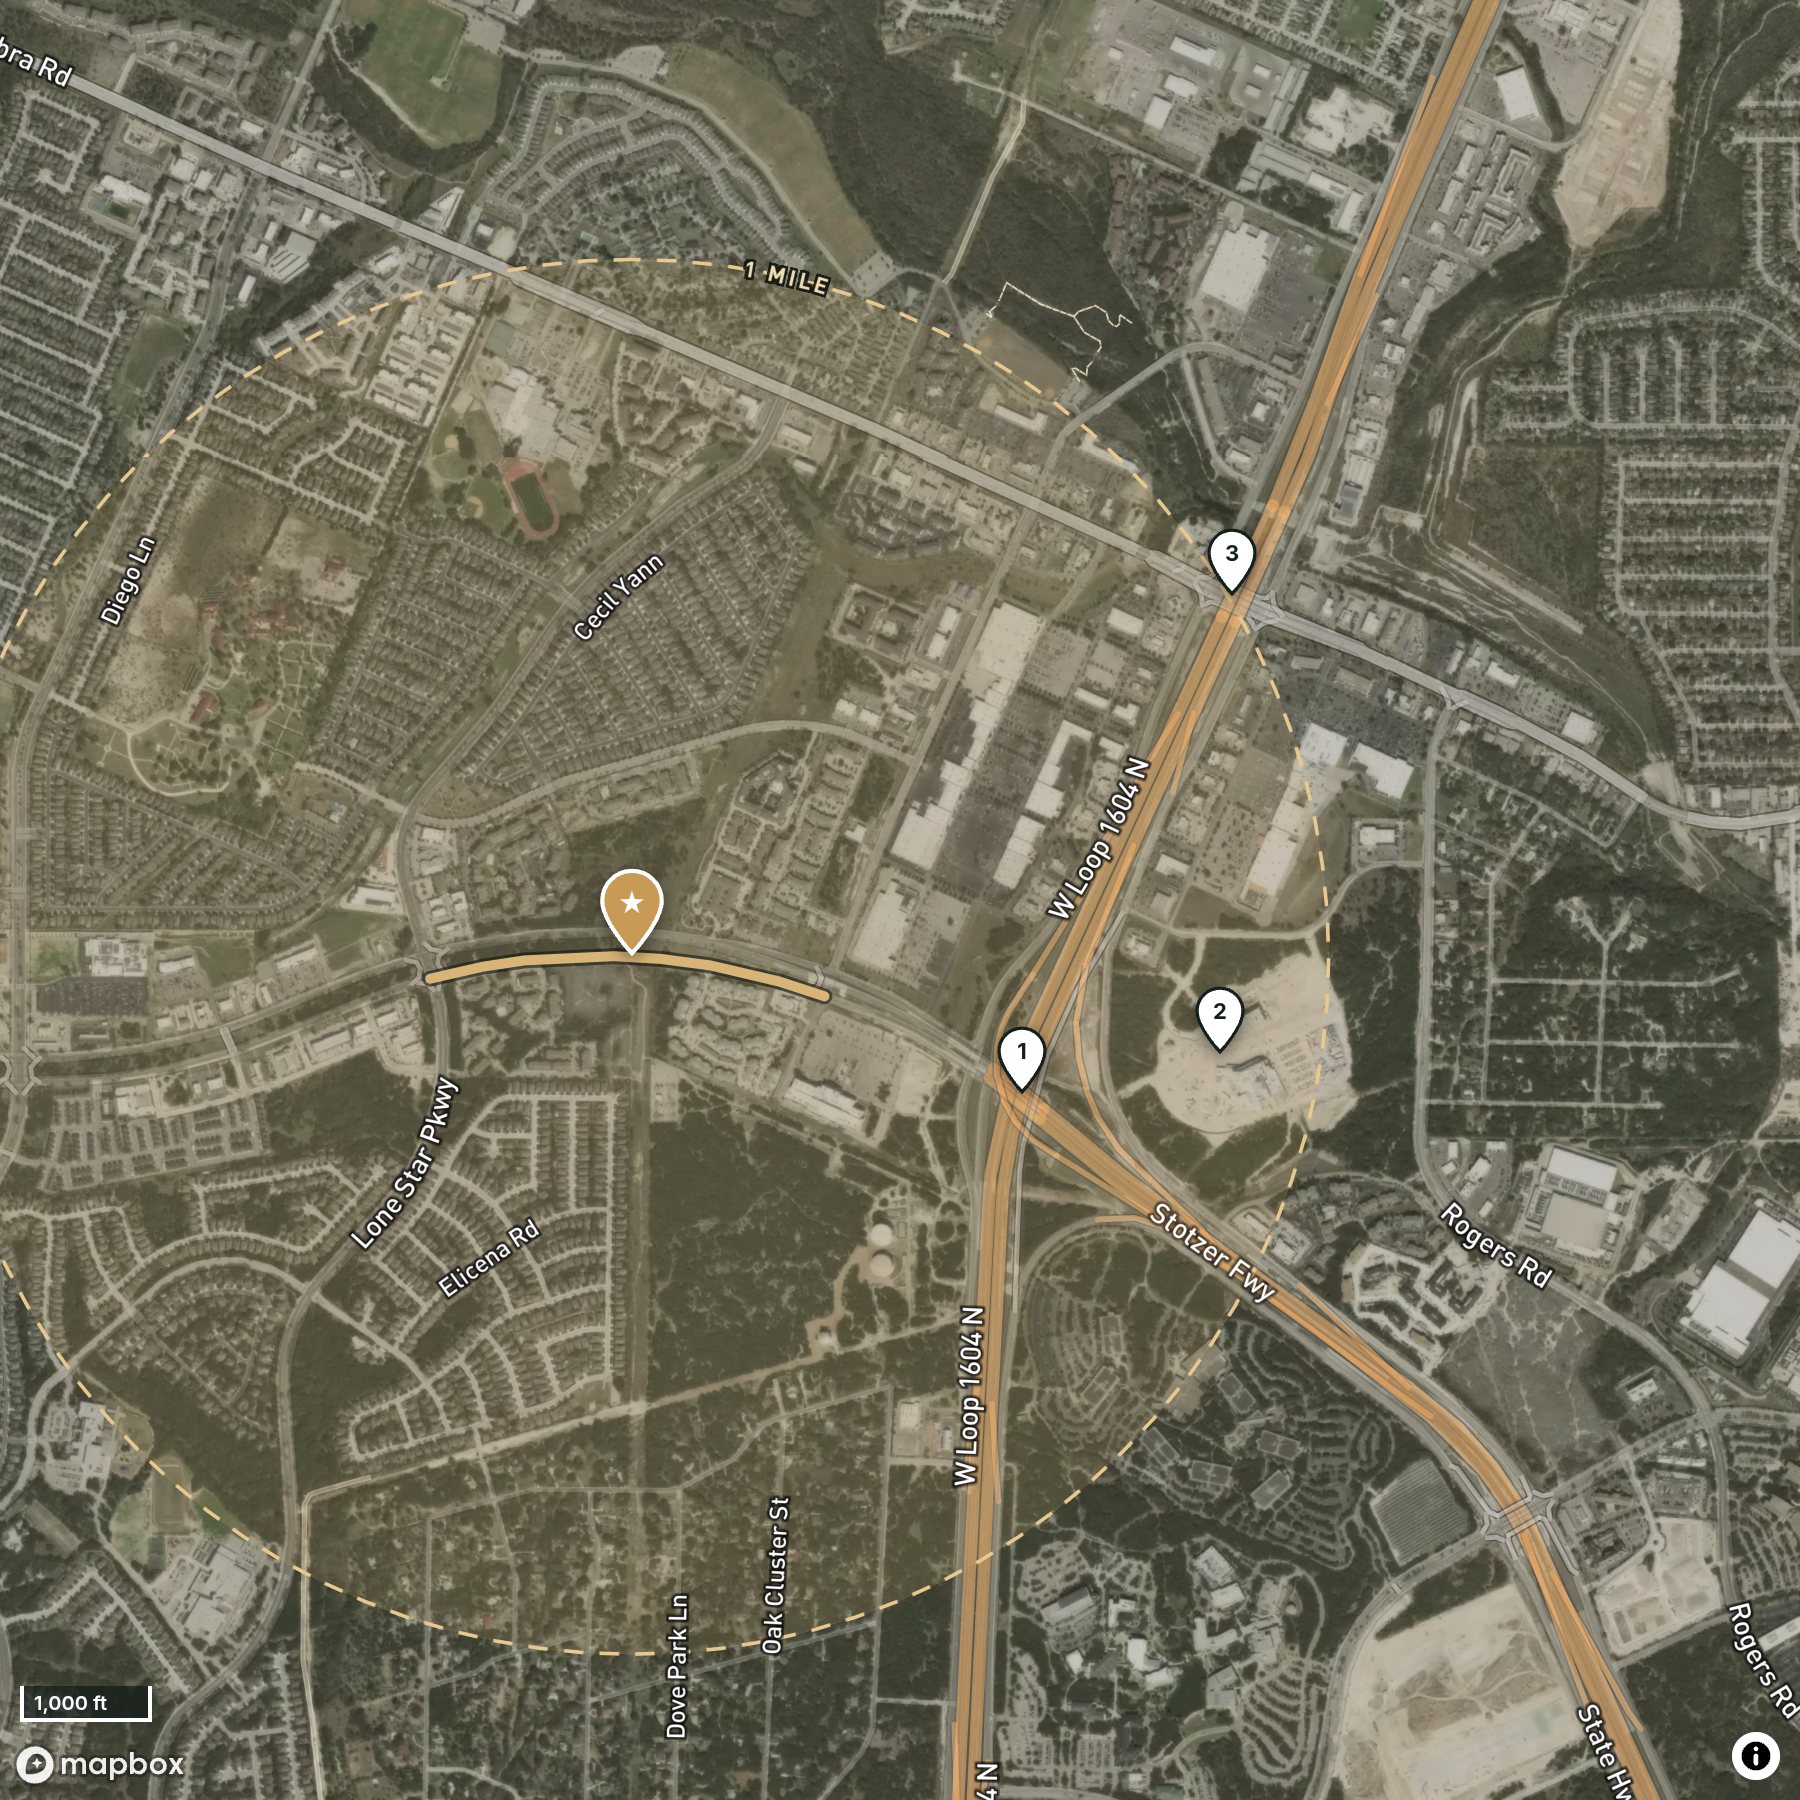
A 2009 center outside Loop 1604.
84,835 SF in 15 suites on 12.82 acres in Alamo Ranch, a master-planned area on San Antonio's Far West Side. A national discount retailer next door anchors the center but is not part of the sale. Five pad lots on 3.89 acres front the parkway and carry no income today.
| Location | Alamo Ranch Parkway, Lone Star Parkway to Westwood Loop, San Antonio, TX 78253 |
| Site | 12.82 acres, including five pads on 169,270 SF of land |
| Occupancy | 73.8%, 12 leases, 22,248 SF vacant in three suites |
| Seller's ask | $13,650,000: center $11,185,000 plus pads $2,465,000 |
Twelve leases, three vacancies, eight rolls by 2028.
| Suite | Tenant | Type | SF | Rent/SF | Annual base | Expires | Lease |
| 425 | Water filtration retailer | In-line | 6,300 | $12.00 | $75,600 | Dec 2027 | Gross |
| 435 | Vacant, seasonal temporary tenant | Junior anchor | 10,282 | ||||
| 445 | Vacant | Junior anchor | 7,737 | ||||
| 455 | Children's entertainment | Junior anchor | 14,358 | $15.00 | $215,370 | Nov 2035 | NNN |
| 465 | Pet supply, national | Junior anchor | 12,600 | $12.00 | $151,200 | Feb 2028 | NNN |
| 475 | Bookstore, regional chain | Junior anchor | 8,400 | $13.75 | $115,500 | Jul 2029 | NNN |
| 635 | Nail spa | In-line | 2,736 | $26.62 | $72,832 | Nov 2037 | NNN |
| 639 | Dental office | In-line | 2,192 | $25.30 | $55,458 | Aug 2030 | NNN |
| 643 | Boutique fitness | In-line | 3,650 | $22.95 | $83,768 | Dec 2028 | NNN |
| 645 | Tanning salon, national | In-line | 2,228 | $20.00 | $44,560 | Feb 2028 | NNN |
| 651-653 | Vacant | In-line | 4,229 | ||||
| 661 | Equipment retailer | In-line | 2,481 | $23.10 | $57,311 | Mar 2027 | NNN |
| 663 | Body care retailer, national | In-line | 3,946 | $25.00 | $98,650 | Jun 2027 | Gross |
| 670 | Body care retailer, storage | In-line | 2,112 | $15.00 | $31,680 | Jun 2027 | Gross |
| 677 | Cookie franchise | In-line | 1,584 | $25.98 | $41,152 | Jul 2027 | NNN |
| Total | 84,835 | $12.30 | $1,043,081 | WALT 3.8 yrs |
We apply a 75% renewal probability at market terms and convert the three gross leases to NNN at rollover.
Our Year 1 NOI is $211,131 below the marketed $914,568.
| Line | Offering | Our underwriting |
| Vacancy and credit | None on the junior anchors | 5% vacancy plus 1% credit loss on every tenant |
| Rent | Contractual bumps projected | Held flat; bumps are upside |
| Management fee | About $42,138 | 4% of effective gross revenue, $56,009 in Year 1 |
| Insurance | $19,493, $0.23/SF | $97,560, $1.15/SF. Trailing actuals run near $0.50/SF, so this is deliberately conservative |
| Utilities and R&M | $117,359 and $89,275 | $148,809 and $148,309, annualized January to July 2026 actuals |
| Non-recoverable G&A | Omitted | $17,273, from the operating statement |
| Seasonal suite | Temporary rent counted as income | Treated as vacant lease-up |
| Gross leases | Recover nothing in place | Convert to NNN at 2027 rollover |
Closing costs 1%, acquisition fee 1.5%, expense growth 3%, a 10-year analysis with a 5-year hold and a 7.50% terminal cap.
About three quarters of the added load is recovered from NNN tenants, which is why the expense increase is larger than the NOI gap.
| Junior anchor boxes | $14/SF NNN, 12 months down, $30/SF TI |
| In-line suites | $18/SF NNN, 9 months down |
| Rollover | 75% renewal probability at market |
| Comp set | $18 to $29/SF in-line asking rents |
NOI reaches $1,221,348 by Year 3 as the vacancy leases.
| Year ending August | 2027 | 2028 | 2029 | 2030 | 2031 |
| Scheduled base rent | 1,027,392 | 1,282,248 | 1,357,920 | 1,387,288 | 1,399,405 |
| Expense recoveries | 406,650 | 627,671 | 690,276 | 724,173 | 760,713 |
| Other income | 50,706 | 50,706 | 50,706 | 50,706 | 50,706 |
| Vacancy and credit loss | (84,511) | (110,854) | (118,524) | (121,981) | (124,535) |
| Effective gross revenue | 1,400,237 | 1,849,771 | 1,980,378 | 2,040,186 | 2,086,289 |
| Operating expenses | (696,800) | (734,005) | (759,030) | (781,817) | (804,667) |
| Net operating income | 703,437 | 1,115,766 | 1,221,348 | 1,258,369 | 1,281,622 |
| Tenant improvements and commissions | (128,574) | (777,913) | (338,157) | (129,780) | (23,678) |
| Capital reserves | (42,417) | (43,690) | (45,001) | (46,351) | (47,741) |
| Property cash flow | 532,446 | 294,163 | 838,190 | 1,082,238 | 1,210,203 |
Unlevered cash flow from the model. Purchase plus closing of $12,301,800 at time zero; sale at the end of Year 5 for $16.17M net.
At the opening offer the deal holds 11.8% even at an 8.00% exit.
| Price | 7.00%exit cap | 7.25%exit cap | 7.50%modeled | 7.75%exit cap | 8.00%exit cap |
|---|---|---|---|---|---|
| $13.65M$161/SF · ask | 9.7%1.54x | 9.0%1.50x | 8.4%1.46x | 7.8%1.42x | 7.2%1.39x |
| $13.02M$153/SF | 10.8%1.62x | 10.1%1.57x | 9.5%1.53x | 8.9%1.49x | 8.3%1.45x |
| $12.60M$149/SF | 11.6%1.67x | 10.9%1.63x | 10.3%1.58x | 9.7%1.54x | 9.1%1.50x |
| $12.18M$144/SF · target basis | 12.4%1.73x | 11.7%1.68x | 11.1%1.64x | 10.5%1.59x | 9.9%1.55x |
| $11.76M$139/SF | 13.3%1.79x | 12.6%1.74x | 12.0%1.69x | 11.3%1.65x | 10.8%1.61x |
| $11.34M$134/SF | 14.2%1.86x | 13.5%1.81x | 12.8%1.76x | 12.2%1.71x | 11.6%1.67x |
| $11.26M$133/SF · opening offer | 14.3%1.87x | 13.7%1.82x | 13.0%1.77x | 12.4%1.72x | 11.8%1.68x |
| $10.92M$129/SF | 15.1%1.93x | 14.4%1.88x | 13.8%1.82x | 13.1%1.78x | 12.6%1.73x |
Unlevered, 5-year hold. IRRs count price plus 1% closing; carrying the 1.5% acquisition fee lowers each by about 36 bps.
Property cash flow after TI, commissions and reserves, over the $12,301,800 basis. Year 2 carries the lease-up capital.
Six swing items, and where each one sits in the model.
Four tenants, about 28,000 SF, hold co-tenancy rights tied to the shadow anchor, which we would not own. Its closure triggers percentage rent, abatement or termination.
MitigantConfirm each clause in the lease abstracts and require estoppels. The exposure supports the opening price.
Utilities and repairs run at annualized 2026 actuals, well above the offering. Seven months of repairs may include pre-sale catch-up spend.
MitigantAbout three quarters of the load is recovered from NNN tenants. Confirm actuals or a normalized figure.
Held at the offering's $228,840, $2.70/SF. A Bexar County reassessment toward the purchase price is a downside the base case does not carry.
MitigantPull the current assessment and protest history before the price is final.
22,248 SF, 26.2% of the center, is vacant. Boxes at $14/SF NNN with 12 months down and $30/SF TI; in-line at $18/SF with 9 months.
MitigantUnderwritten at the bottom of the $18 to $29 comp set. Firm rents, TI and downtime with leasing brokers.
Eight leases, about 35,000 SF, roll by year-end 2028, including the pet supply store at $12/SF.
MitigantChildren's entertainment (2035) and the nail spa (2037) give the term ballast. Gross leases convert to NNN at rollover.
Outparcel income is held flat at $50,706 despite a contractual 25% step in 2029. The seasonal tenant's $35,700 is excluded.
MitigantThe five pads carry zero income and zero residual value in the model.
Proposed first-round terms.
| Price | $11,258,000 · $133/SF |
| Allocation | Center $8,793,000, an 8.00% on Year 1 NOI; five pads $2,465,000, the seller's ask |
| Interest | Fee simple in the center and all five pad lots, 12.82 acres |
| Due diligence | 45 days from the effective date |
| Closing | 30 days after the end of due diligence |
| Conditions | Tenant estoppels confirming co-tenancy status; current Bexar County assessment; 2026 operating statements |
| Authority | Up to $12,180,000 without returning to committee; no bid above $12,758,000 |
Utilities and repairsConfirm annualized actuals or a normalized figure.
The three vacanciesConfirm market rents, TI and downtime.
TaxesSize the reassessment step-up from county data.
Co-tenancyReview the four anchor clauses and the remaining abstracts.
Two ways to build an 8.00% going-in.
| Construction | Price | Going-in | IRR | Multiple |
| 8.00% blended, center and all five pads | $8.79M | 8.00% | 19.3% | 2.27x |
| 8.00% on the center, pads at their ask | $11.26M | 6.25% · 8.00% center | 13.0% | 1.77x |
| Target basis, for reference | $12.18M | 5.78% · 7.24% center | 11.1% | 1.64x |
$11,258,000 pays the full ask on the pad land and an 8.00% on the operating center. It reads as a 7.6% discount to our basis rather than a 28% one. The blended $8,793,000 is an anchor, not an offer: it sits 36% below the $13,650,000 ask and rests on the $211,131 NOI gap and the co-tenancy exposure.
Caps are NOI over purchase price. Measured on total basis including the 1% closing cost, an 8.00% blended requires $8,706,000.